No title? No problem in most cases. Free towing, cash on the spot.
Published October 19, 2026 by Instant Money Junk Cars
Selling a car after a repossession feels complicated, but the sale itself is usually straightforward. A past repo is a credit event, not a permanent mark on the vehicle. If you got the car back, or if you are selling a different car now, the repossession on your record does not block the transfer, and buyers evaluate the vehicle in front of them, not your credit history. Here is how a repo history affects a sale and the cleanest way to move on.
This is general information about how vehicle sales typically work after a repossession, not financial or legal advice. Every loan situation has its own terms, so confirm the specifics with your lender. The reassuring core, though, holds in most cases: you can sell, and selling is usually the smartest move you can make right now.
In most cases, yes. If the repossession was on a previous car, it has no bearing on selling your current one; the repo lives on your credit report, not on the new car's title. If the repo was on this car and you redeemed it, meaning you paid what the lender required to get it back, then you hold it normally again and can sell it like any other vehicle you own.
The situation to check is whether the lender still holds the title. If there is an active lien, the loan must be satisfied at the time of sale, exactly like any financed car. Our page on selling a car with a loan walks through how the payoff works at transfer, including how a buyer and lender coordinate so the title clears cleanly.
Not in the way most sellers fear. A repossession appears on your credit report. It does not generally appear on the car's title or in the vehicle history a buyer pulls. The buyer is evaluating the car's condition, mileage, and title status, not your payment history. You do not need to volunteer your credit story, and a buyer has no legitimate reason to ask for it.
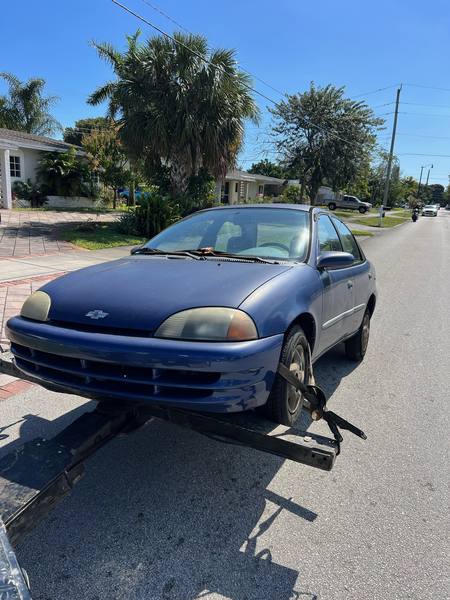
What the buyer will see is the title: clean, lien, rebuilt, or otherwise. Keep the title side clean by making sure any lien release from the redeemed loan is properly recorded. When a repossessed car is redeemed, the lender issues a satisfaction of lien, and that release needs to reach the state records. If it never got recorded properly, the title can still show the old lien, which confuses buyers and slows the sale. A quick check of the title status before you list, and a call to the lender if anything looks stale, clears this up in days. Clean title paperwork is what lets the sale close on the spot instead of stalling on a records question. If paperwork from the repo period is messy, a few calls to the lender now save confusion at the sale. And when the money arrives, our guide to how you get paid when selling a car covers what to expect at closing.
A deficiency balance, the gap between what you owed and what the lender got for the car at auction, is a debt between you and the lender. It does not attach to a different car you own now, and it does not block you from selling your current vehicle. It is a separate obligation with its own terms, and in some cases it is negotiable or settled for less than the full amount.
Do not let the deficiency freeze you. Some borrowers avoid selling a current car because the old debt feels entangled with it, but the two are legally distinct. Selling the car you have now, especially if the payments are a strain, is often what stops the next repo from happening. If you are carrying more loan than the car is worth, our page on upside-down car loans explains the options plainly.
Almost always. A voluntary sale lets you control the price, choose the timing, and satisfy as much of the loan as possible. A repossession hands all of that to the lender, who sells at auction, often for less than you would get, and bills you the deficiency. The credit impact of a second repo is also more damaging than the impact of selling and closing out a loan, even a loan closed at a small loss.
If the repo truck is a real possibility rather than a memory, speed matters more than squeezing the last dollar. Our guide to selling your car before repossession covers the timeline and why acting this week beats acting next month. A cash buyer who closes the same day can be the difference between a sale you control and a tow you do not.
Start with an online junk car quote and be upfront about the loan situation so the payoff can be coordinated. See how junk car pickup works, then sell your car fast with free towing and cash paid on the spot. The sale proceeds go to the lender first, and anything left over is yours.
Past purchases have ranged from $150 to $1,300 with a $525 median across 303 completed buys, and recently purchased vehicles show what cars like yours brought. Call 954-787-5717. A past repo is a chapter, not a life sentence, and a clean sale is how you turn the page.
FAQ
Call 954-787-5717 for a cash offer. Free towing, cash on the spot, pickup usually within about an hour.
954-787-5717
 954-787-5717